Pomerleau Unveils its 2025 Sustainable Development Report
ESG


Canada’s construction industry returned to a positive trajectory in the second quarter of 2026, despite continued economic uncertainty. Activity increased, cost pressures became more concentrated, and the construction labour market showed signs of stabilizing. In this new edition of the Pomerleau Economic Radar, our experts examine four key areas shaping the Canadian construction market: activity, costs, labour and the broader economic environment. The analysis provides construction professionals and public- and private-sector decision-makers with strategic insights to anticipate risks, identify opportunities and plan projects more effectively.
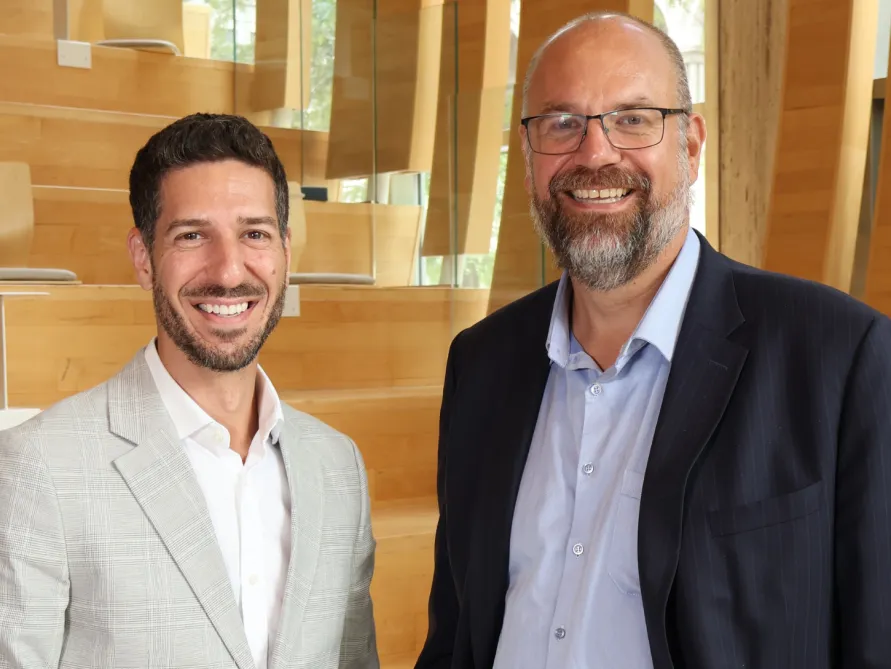
The Pomerleau Economic Radar combines the field experience of Sean Boyer, Eng., PQS, Vice President, Preconstruction – Buildings, with the analytical expertise of Jean-François Perras, C.Adm., ECCQ, Manager, Economic and Statistical Expertise – Buildings.
Sean Boyer connects market trends with preconstruction strategies and project delivery conditions, while Jean-François Perras structures and analyzes data to identify the economic signals that matter most to the construction industry. Supported by their colleagues, they provide a market perspective that helps clarify changing conditions and their implications for construction decisions.
Following a hesitant start to the year, construction GDP increased by 1.06% quarter over quarter, supported in particular by engineering construction and other construction activities. Investment in building construction also increased, driven primarily by the residential sector.
Building permits provide another encouraging signal for the Canadian construction industry. The value of non-residential building permits jumped 14.08% during the quarter, led by institutional and government projects. This increase will need to be monitored to determine whether it reflects a sustained trend or the impact of a small number of major projects. The recovery therefore remains uneven, with the outlook varying across construction segments.
Non-residential construction prices increased 3.50% year over year in Q2 2026. Cost pressures continue to vary considerably by market: London and Quebec City stand out for their year-over-year increases, while markets in British Columbia recorded more moderate growth.
Construction materials are also following different trajectories. Several commodities declined during the quarter, while some metals remained significantly more expensive than a year earlier. Mechanical and electrical products recorded more limited increases. These differences reinforce the importance of assessing construction costs in Canada according to regional conditions, material categories and the specific requirements of each project.
Canada’s construction labour market is showing signs of stabilization, although employment remains slightly below its level from a year ago. In June, the construction unemployment rate stood at 6.0%, compared with 6.5% across all industries.
At the same time, the construction job vacancy rate increased from 2.9% in March to 3.2% in June, while the unemployed-to-job-vacancy ratio declined, pointing to some tightening over the three-month period. This reinforces an important consideration for project planning: a stabilizing labour market does not necessarily guarantee access to the resources required to deliver projects. Construction workforce planning therefore remains an important factor in successful project delivery.
After reaching a peak in spring 2026, global supply chain pressures eased in the months that followed. They nevertheless remain above their historical average, reinforcing the need for continued vigilance when planning procurement and deliveries.
Trade and geopolitical tensions, along with energy market volatility, continue to affect project predictability. Their impacts can flow through to transportation and production costs, as well as to the price of many materials used in construction. Even in a more stable environment, changes in tariffs and strategic inputs remain important indicators to monitor when anticipating potential project delivery constraints.
These trends reinforce the importance of connecting economic data with on-the-ground project realities from the earliest stages of preconstruction planning. For project owners and their partners, understanding Canadian construction market conditions can support better-informed decisions around budgets, procurement and workforce mobilization. Three priorities stand out:
Accounting for regional market differences and identifying materials most exposed to price fluctuations can help establish budgets that are better aligned with current construction market conditions.
Assessing lead times, product availability and supplier-related risks early can help teams prepare procurement strategies and adjust project schedules accordingly.
Integrating labour requirements into project planning and maintaining close coordination between design, preconstruction and project delivery teams can strengthen the ability to adapt as market conditions evolve.
By combining economic expertise with in-depth project knowledge, Pomerleau provides insights that help decision-makers manage risk more effectively and build with confidence.
Discover the Pomerleau Economic Radar Q2 2026 for detailed analysis, regional data and the key Canadian construction trends to watch in the coming quarter.